Inflation refers to the gradual increase in prices for goods and services over time. As prices rise, consumers need more money to purchase everyday essentials and maintain their standard of living.
In Canada, inflation is closely monitored because it influences economic stability, consumer confidence, and business growth. Moderate inflation is considered healthy, while excessive inflation can create financial challenges for households.
Several factors contribute to inflation, including supply chain disruptions, higher production costs, increased consumer demand, and global economic events. These influences affect prices across multiple sectors of the economy.
Understanding inflation helps Canadians make informed financial decisions. By recognizing how price changes impact spending power, households can better manage budgets and prepare for future economic conditions.
One of the most noticeable effects of inflation is the increase in everyday living costs. Families often experience higher expenses for groceries, transportation, housing, and utility services.
Food prices can fluctuate due to transportation costs, weather conditions, and supply shortages. As grocery bills increase, households may adjust purchasing habits and prioritize essential items over discretionary spending.
Housing expenses also play a significant role in household budgets. Rising rents, mortgage payments, and maintenance costs can place additional pressure on families attempting to balance monthly financial obligations.
Utility costs, fuel prices, and household necessities often rise alongside inflation. These cumulative increases can reduce disposable income and make long-term financial planning more challenging for many Canadians.
As inflation affects purchasing power, consumers often modify spending behaviors to manage rising costs. Many households become more selective about purchases and focus on value-driven decisions.
Canadians increasingly compare prices, search for discounts, and purchase products during promotional periods. These strategies help families stretch budgets while maintaining access to essential goods and services.
Non-essential spending frequently declines during periods of higher inflation. Entertainment, travel, luxury purchases, and recreational activities may receive less priority when household expenses continue increasing.
Digital shopping platforms have also influenced spending habits. Consumers can compare products more easily, identify competitive prices, and make informed purchasing decisions that support financial efficiency.
Inflation and interest rates are closely connected within Canada's financial system. Policymakers often adjust interest rates to influence economic activity and help maintain price stability over time.
When inflation rises significantly, higher interest rates may be introduced to reduce spending and borrowing. This approach can help slow demand and ease upward pressure on prices.
For households, increased interest rates often result in higher borrowing costs. Mortgage payments, personal loans, and credit card balances may become more expensive, affecting monthly financial commitments.
On the other hand, higher interest rates can encourage saving. Individuals may benefit from improved returns on savings accounts and investment products designed to support long-term financial goals.
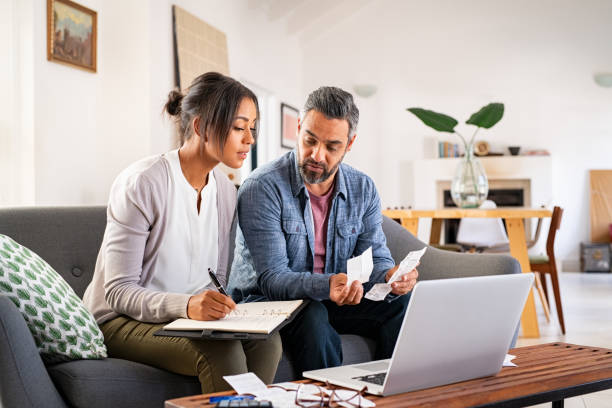
Many Canadian households are reviewing financial priorities to adapt to inflationary pressures. Careful budgeting has become an important tool for maintaining financial stability during uncertain economic periods.
Families often track monthly expenses more closely and identify opportunities to reduce unnecessary spending. Small adjustments can create meaningful savings that help offset rising living costs.
Meal planning, bulk purchasing, and reducing waste are common strategies used to manage grocery expenses. These practical approaches allow households to maximize value while controlling food budgets.
Many consumers are also focusing on emergency savings and debt reduction. Building financial resilience helps households navigate unexpected expenses and maintain greater control over personal finances.
Inflation does not affect all households equally. The impact often depends on income levels, spending patterns, employment circumstances, and the proportion of income dedicated to essential expenses.
Lower-income households may experience greater financial pressure because a larger share of their earnings is allocated toward necessities such as housing, food, and transportation services.
Middle-income families often face challenges balancing rising expenses with long-term financial objectives. Saving for education, retirement, or homeownership may become more difficult during inflationary periods.
Higher-income households may have greater flexibility to absorb increased costs. However, they can still experience financial adjustments as investment strategies, purchasing decisions, and economic expectations evolve.
Persistent inflation can influence broader economic conditions beyond household budgets. Consumer confidence, business investment decisions, and overall economic growth may be affected by prolonged price increases.
Businesses often face higher operating expenses, including labor, materials, and transportation costs. These expenses may contribute to additional price increases that impact consumers and market demand.
Inflation can also influence wage growth as employees seek compensation adjustments to maintain purchasing power. Employers and workers must balance labor costs with economic competitiveness and productivity goals.
Over time, stable inflation management supports economic confidence and sustainable growth. Effective policies help create conditions that encourage investment, employment opportunities, and financial security for Canadians.
While inflation levels may fluctuate, households can take proactive steps to strengthen financial preparedness. Planning ahead can reduce stress and improve confidence during changing economic conditions.
Creating realistic budgets allows individuals to understand spending patterns and identify areas where adjustments may be necessary. Consistent monitoring supports better financial decision-making and long-term stability.
Diversifying income sources can provide additional financial flexibility. Side businesses, freelance work, and professional development opportunities may help households increase earnings and offset rising costs.
Financial education remains one of the most valuable tools for managing inflation. Understanding economic trends, saving strategies, and responsible spending practices helps Canadians navigate future challenges successfully.
Canada’s inflation trends continue to influence household spending patterns, budgeting decisions, and financial planning strategies. Rising prices affect essential expenses and encourage consumers to adapt their purchasing behaviors.
Understanding the relationship between inflation, interest rates, and consumer spending can help households make informed decisions. Knowledge of economic trends supports stronger financial management and preparedness.
Many Canadians are responding by adjusting budgets, prioritizing savings, and focusing on value-based spending. These strategies help maintain financial stability despite ongoing economic changes.
As inflation continues to evolve, staying informed and planning carefully will remain important. Households that adopt proactive financial habits are better positioned to manage costs and achieve long-term financial goals.
This post has been authored and published by one of our premium contributors, who are experts in their fields. They bring high-quality, well-researched content that adds significant value to our platform.
Canada Trends is your trusted source for trending news, lifestyle insights, business updates, technology developments, entertainment stories, and informative content from Canada and around the world.